

First 40 weeks of 2026 at FPMs
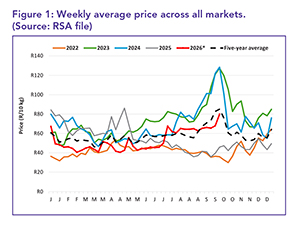
The average weekly price of potatoes during the first 40 weeks of 2026 at South Africa’s fresh produce markets (FPMs) rose 18% week on week. Figure 1, which tracks the weekly average price across all markets, potato classes, and sizes, shows the average price in week 40 at R79.82 per 10 kg bag. This represents a year-on-year increase of R33.92 compared to the corresponding week in 2025, underscoring continued price volatility and market fluctuations.
Stock levels and price trends
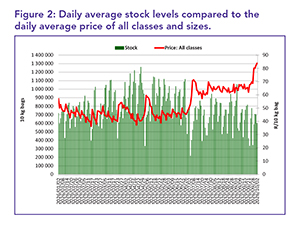
Figure 2 illustrates the relationship between supply and demand by analysing daily average stock levels alongside price trends. Lower stock levels typically exert upward pressure on prices. During September 2026, the average daily stock across South African FPMs was 657 789 bags (10 kg), representing a 25% year-on-year decrease from the September 2025 average of 878 542 bags (10 kg).
Sales volumes and trends
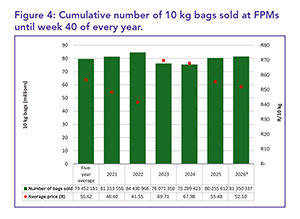
Figure 3 presents a year-on-year comparison of monthly sales volumes, showing a 12% decrease in September 2026 relative to September 2025. Cumulative sales for the first 40 weeks of 2026 totalled 81.4 million 10 kg bags, which is 1 898 156 bags above the five-year average, as shown in Figure 4. Notably, the average price for the first 40 weeks in 2026 is R4.52 lower than the five-year average.
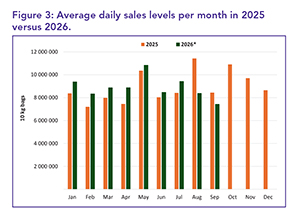
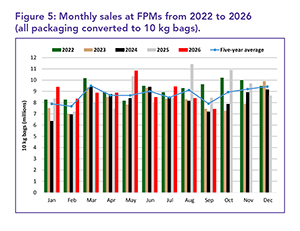
Monthly sales trends at FPMs, depicted in Figure 5, show a month-on-month decrease, with September 2026 recording 7.4 million 10 kg bags sold, compared to 8.4 million bags in August 2026. This represents a decrease in volume of 956 630 bags (10 kg).
Bag sales and averages
Table 1 outlines the number of bags sold at the various FPMs during September 2026. The five biggest markets accounted for 83.9% of the country’s sales, underscoring their pivotal role in the potato supply chain. Table 1 also shows the average price per 10 kg bag for September across all classes and sizes, at R66.14.
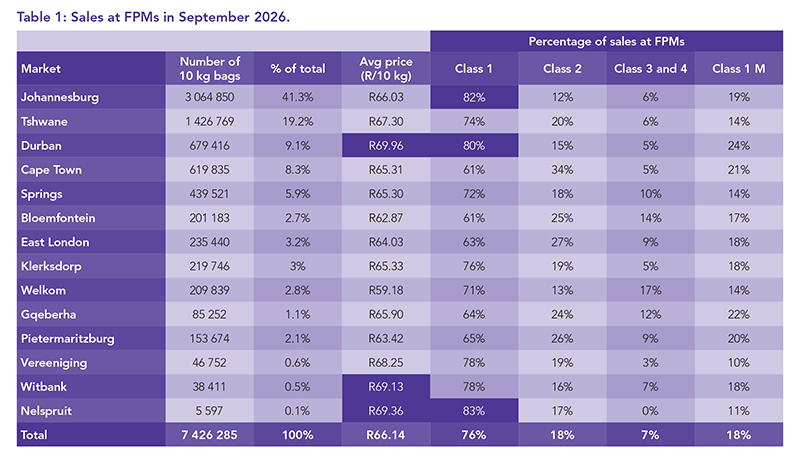
Regarding the top average price per 10 kg bag received at the markets during September, Durban Market led with R69.96, followed by Nelspruit Market at R69.36 and Witbank Market at R69.13. In terms of Class 1 (all sizes) sales, the Nelspruit, Johannesburg, and Durban Markets recorded the highest distribution at 83, 82, and 80%, respectively. Among the top three markets, Nelspruit ranked the highest.
Figure 6 illustrates the year-on-year price change at the top five markets for September 2026, with all five markets showing increases. Durban Market showed the largest percentage increase at 75.1%, compared to September 2025. Cape Town Market showed the lowest percentage price increase at 65%.
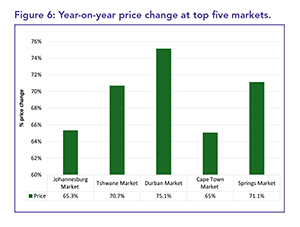
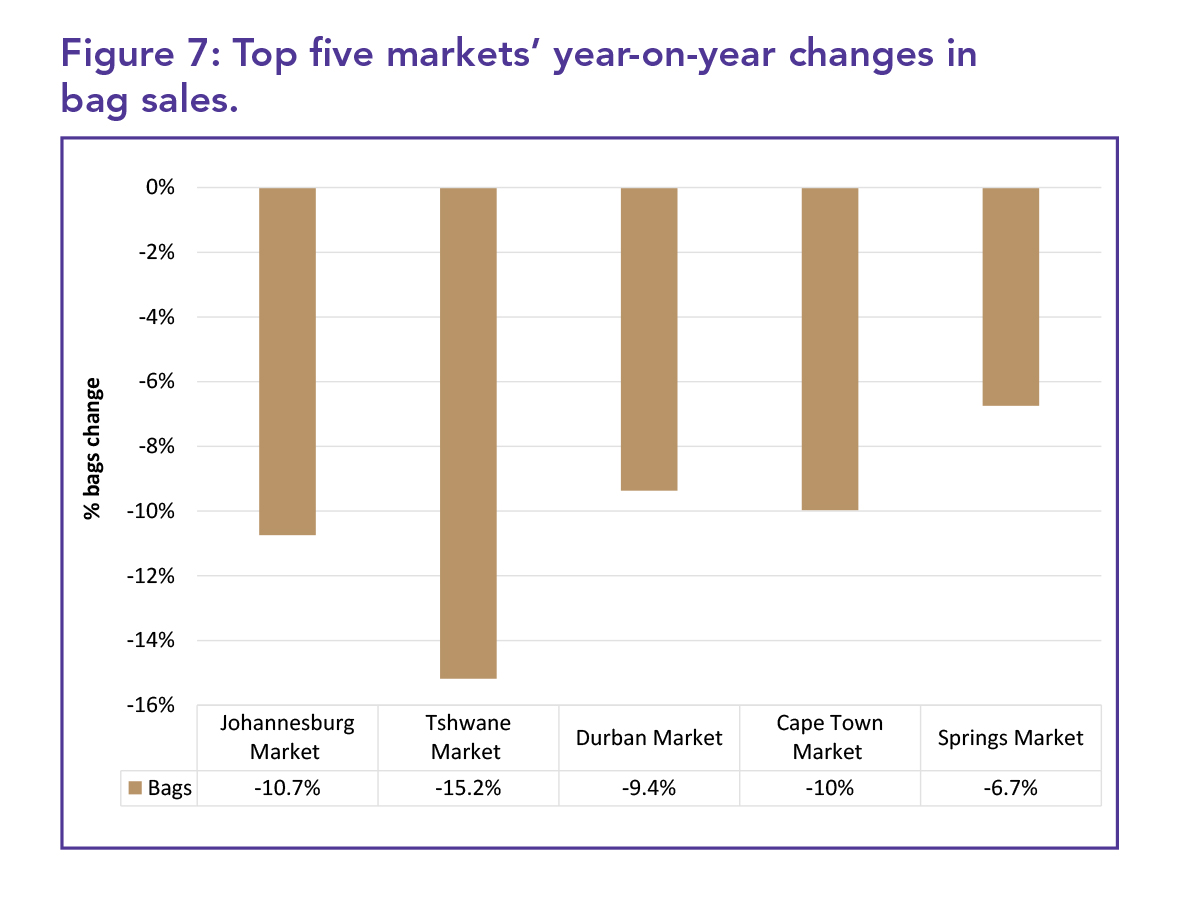
Figure 7 highlights the year-on-year percentage change in sales volumes for the top five markets for September 2026, with Tshwane Market showing the largest decrease at 15.2%.
Regional performance
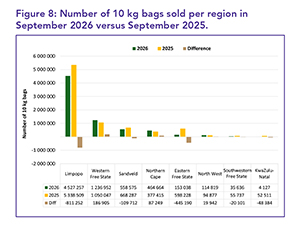
Figure 8 illustrates regional sales performance, with Limpopo recording the highest volumes of 4.5 million 10 kg bags, reaffirming its position as the market leader in September 2026. The region recorded a 15% year-on-year volume decline. The Western Free State recorded a year-on-year increase of 18%, and the Sandveld a 16% decrease. Limpopo, the Western Free State, the Sandveld, the Northern Cape, and the Eastern Free State collectively accounted for 93% of total national potato sales in September 2026, as summarised in Table 2.
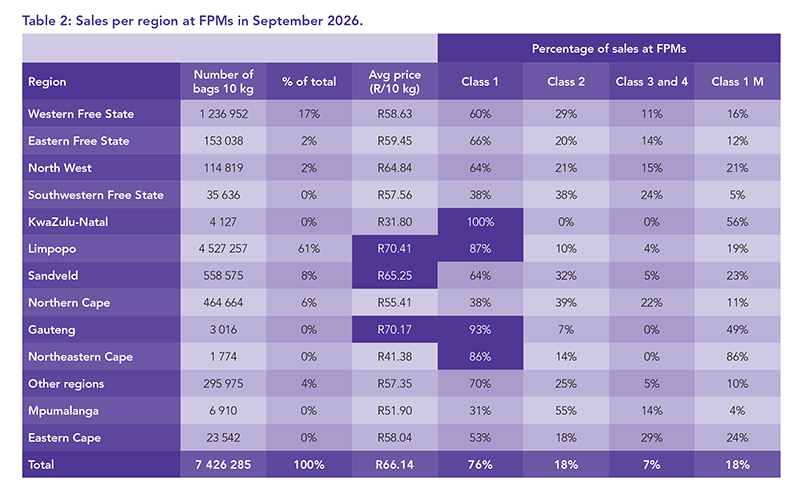
Potato classification also varies by region, as shown in Table 2. Regions such as KwaZulu-Natal, Gauteng, Limpopo, and the Northeastern Cape led in Class 1 sales, with 100, 93, 87, and 86% of their sales falling into this premium category, respectively. Overall, five of the 14 regions maintained a Class 1 sales ratio above 70%, indicating variability in quality across some regions. – Lebo Tlomatsana and Anjé Venter, Potatoes SA
For more information, email Lebo Tlomatsana at lebo@potatoes.co.za.